- OUE saw recovery in its revenue in FY21 and FY22, and this trend is likely to continue in 2023.
- We are optimistic in its Hospitality segment with the global rebound in tourism, and also the Healthcare segment which provides for a more stable income.
- OUE has a decent credit profile but cash position weakened. However, refinancing should not be a major issue.
- We recommend OUESP 3.500% 21Sep2026 Corp (SGD) for its
optimal yield-to-maturity, which is complemented with a short to medium term
maturity period.
Introduction
OUE Limited (“OUE”) is a real estate development, investment and management company with assets across Asia. It endeavours into a variety of sectors, including commercial, hospitality, retail, residential as well as healthcare. At the same time, OUE performs as the manager of two Real Estate Investment Trusts (“REIT”) – OUE Commercial REIT (“OUE C-REIT”) and First REIT, where both are a subsidiary under OUE itself.
Chart 1Assets
by Geographical Region as of FY22
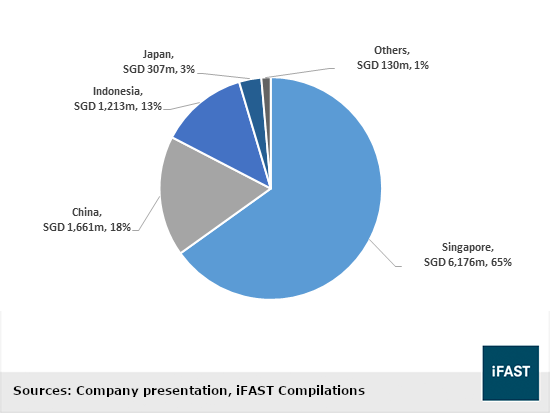
OUE primarily classifies its operations into three business segments – Real Estate (which includes Investment Properties, Hospitality and Development Properties), Healthcare and Consumer. The majority of its assets are located in Singapore at 65% as observed in Chart 1. As of 31 December 2022, the total value of the assets managed by OUE amounts to approximately SGD 9.5b, while the aggregate funds in management under the two REITs amount to approximately SGD 7.8b.
Of its recent development, a significant milestone for OUE was the completion of full refurbishment works of Hilton Singapore Orchard, with the unveiling of the Orchard Wing comprising 446 rooms. Asset enhancement initiatives for the hotel had previously begun in March 2020, which was partially completed in February 2022 alongside the re-opening of the Mandarin Wing.
Financial Highlights
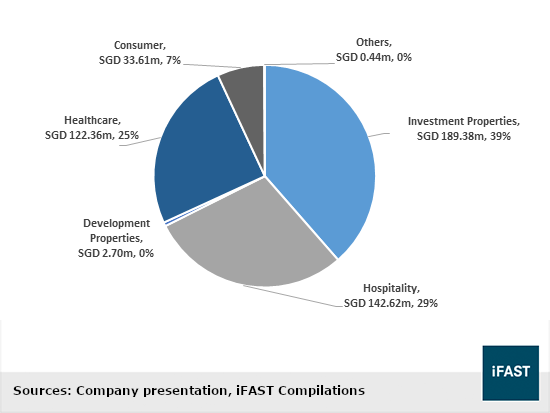
For the financial year ended 31 December 2022 (“FY22”), the Real Estate segment continues to be the main driver of the business, bringing in 68% of the Group’s Turnover (collectively under Investment Properties, Hospitality and Real Estate Development) as shown in Chart 2. On the other hand, we see the increased contribution by the Healthcare segment, rising to 25% in FY22 as compared to 10% in FY21, which was largely due to the accounting of First REIT as a subsidiary since 1 March 2022.
Chart 2Group
Turnover by Business Segments as of FY22
In FY22, we saw a substantial rise in the profit after tax at SGD 347m, as compared to SGD 101m in FY21 – which had been a reasonable recovery after losses amounting to SGD 405m in FY20 due to COVID-19. While it appeared to be a considerable recovery with the relaxation of COVID-19 policies in 2022 for Singapore, we noted a large proportion of the profit came from other gains amounting to SGD 149.5m. This particular source of profit had no direct relation to its business operations, primarily arising from the reversal of impairment of assets and negative goodwill related to its subsidiaries.
On a
similar note, OUE had separately recorded a fair amount of loss due to currency
translation differences at approximately SGD 288m in its other comprehensive
income. We believe this is likely due to a portion of assets located in
Indonesia, and that IDR had fallen off significantly to SGD across 2022. This
resulted in the significant currency translation difference with the assets
having to be reported in SGD.
While these factors appear to discount the growth that OUE had undergone in FY22, OUE’s outlook remains optimistic particularly in its Real Estate – Hospitality segment, and Healthcare segment. With the complete reopening of Hilton Singapore Orchard, and being the flagship Hilton hotel across Asia, the hotel is expected to contribute further towards the rapidly recovering Hospitality segment. The relaxation of COVID-19 policies in 2022 had enabled the turnover from Hospitality to rise from SGD 57m to SGD 142m, and this figure is likely to continue increasing with a global travel rebound in 2023.
Concurrently, greater diversification of its operations into the Healthcare segment should benefit the business. Since 2022, OUE had been further developing its Healthcare business – a medical partnership with three medical specialist groups in Singapore via a joint venture company, Echo Healthcare Management Pte. Ltd. which OUE holds a 60% stake, and a partnership with the Chinese University of Hong Kong for management consultancy on its Shenzhen China Merchants-Lippo Prince Bay Hospital in Shekou, Shenzhen. This diversification should allow for greater stability in income for OUE, especially with the real estate sector temporarily hindered by the high-interest rates environment.
Credit and Liquidity Profile
Coming to its liquidity, OUE saw a relatively large outflow of cash and cash equivalent in FY22 amounting to an overall SGD 161.5m, which is approximately 33% of its cash position. This leaves OUE in a cash position of SGD 326m as of FY22. The usage of cash is exceptionally high as compared to the past years, forming a much smaller proportion of its total cash and cash equivalents.
In addition to this, investors might want to note that OUE’s earnings had a significant proportion contributed by the share of results of equity-accounted investees with SGD 157m in FY22. This represents approximately ~45% of its profit after tax and might be a limiting factor in OUE’s cashflow from operations even as we see improving overall operations in the future.
Looking at OUE’s borrowings, the total short-term borrowings amount to SGD 578m, which OUE is likely to rely on refinancing as its cash and cash equivalent might be insufficient to cover the maturing debts. Notably, OUE had recently redeemed SGD 200m in principal value of the OUESP 3.550% 10May2023 Corp (SGD) – without issuing a new note to finance the redemption.
Across its total borrowings of SGD 2,967m, approximately ~33% are secured borrowings. With this information in mind, and looking at OUE’s attempts at raising funds, we do not believe it would face issues in getting fundings, particularly with further room for secured borrowings. However, assuming that all of OUE’s bank borrowings are on a floating-rate basis, accounting for an estimated ~66% of its borrowings, OUE ought to borrow with greater prudence given the burgeoning interest expenses in the current environment.
Overall, OUE is likely to face limitations in being able to utilise its cash freely, considering its thin cashflow from operation and debt repayment obligations. Nonetheless, we do not think this would translate into problems for OUE in refinancing its debts. Its credit profile is likely to stay decent in the short-term, especially with hospitality expected to continue outperforming in these recent years to provide the much-needed cashflow.
Recommendations
Table 1Fixed Rate issuances from OUE and
related entities
|
Issue |
Ask Price |
Yield to Maturity |
Years to Maturity |
|
94.85 |
5.30% |
3.27 |
|
|
97.23 |
5.05% |
3.89 |
|
|
98.00 |
4.68% |
2.96 |
|
|
98.88 |
4.65% |
2.02 |
|
|
97.90 |
3.85% |
3.81 |
|
|
Sources: Bondsupermart, iFAST Compilations. Data as of 16 June 2023. |
|||
Across the fixed rate issuances by OUE and its related entities, we have a preference for OUESP 3.500% 21Sep2026 Corp (SGD) given the higher yield to maturity at maturity periods left. With 3.27 years left to maturity, the note offers a yield to maturity of 5.30% at the ask price of 94.85.
Given a relatively small issuance size of SGD 200m, OUE is quite unlikely to face issues refinancing the debt. In addition, with the maturity date in 2026, there is ample time for policy rates to stabilise from here onwards – with US Federal Reserve recently pausing rate hike efforts. We believe the OUE would be able to refinance at a lower cost, given improvements to its credit profile as it recovers from the COVID-19 impact alongside a more optimal interest rate environment.
In this post-COVID era, we believe OUE has further room for improvement especially in an environment of recovering tourism. We are optimistic about its outlook in the upcoming years, but we also see a need for OUE to manage its capital more carefully in this high-interest rates environment. In our view, OUESP 3.500% 21Sep2026 Corp (SGD) would be optimal for investors looking for options in the short to medium term.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OUECT 3.950% 02Jun2026 Corp (SGD), FIRTSP 3.250% 07Apr2027 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!